
Silicon Carbide (SiC) Wafer Market to Reach USD 3.1 Billion by 2034 as 8-Inch Manufacturing Gains Momentum
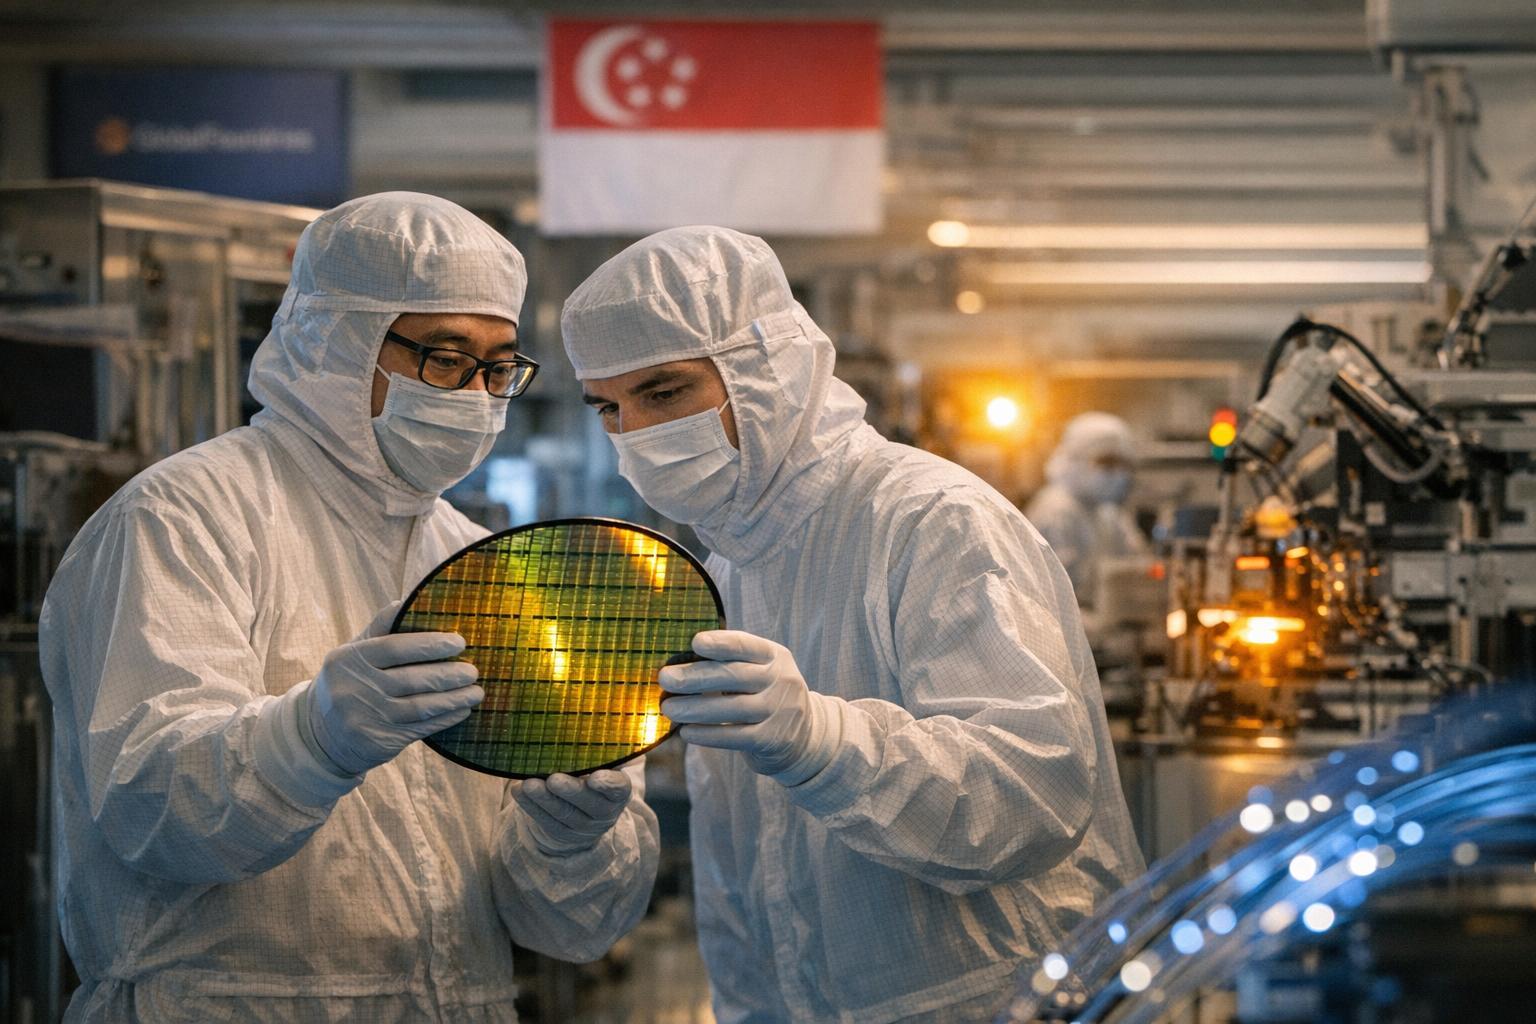
The power semiconductor industry is increasing its use of wide-bandgap materials as electric vehicles, renewable-energy systems and high-power electronics require efficient operation at elevated voltages and temperatures. Silicon carbide wafers are central to this transition because they provide the substrate platform for manufacturing power devices designed for demanding electrical and thermal conditions.
According to Semiconductor Insight, the Global Silicon Carbide (SiC) Wafer (6-inch, 8-inch) Market was valued at USD 910 million in 2025 and is expected to reach USD 3.1 billion by 2034, growing at a CAGR of 14.8% over the 2026–2034 forecast period. The market’s development is closely linked to demand for SiC power devices and the transition from established 6-inch wafer production toward larger 8-inch formats.
Explore the complete Silicon Carbide (SiC) Wafer (6-inch, 8-inch) Market analysis: https://semiconductorinsight.com/report/silicon-carbide-sic-wafer-6-inch-8-inch-market/
Why Are Silicon Carbide Wafers Becoming Important in Power Semiconductor Manufacturing?
Silicon carbide is a wide-bandgap semiconductor material used to manufacture power devices that operate in high-voltage and high-temperature environments. Its material properties support power conversion designs that require efficient switching and thermal performance.
SiC wafers are used as substrates for devices such as MOSFETs and Schottky diodes. These components are deployed in electric-vehicle powertrains, charging systems, renewable-energy equipment and industrial power electronics.
The report focuses on 6-inch (150 mm) and 8-inch (200 mm) wafer formats. Wafer diameter is an important manufacturing consideration because it influences the number of potential device dies that can be produced from a wafer and the economics of fabrication.
As power-device demand expands, wafer suppliers and semiconductor manufacturers are evaluating larger diameters to improve production scalability and support the next stage of SiC manufacturing.
Market Growth Is Closely Linked to Electric Vehicles and High-Power Electronics
Electric vehicles are an important demand source for SiC wafers because powertrain systems use power semiconductors to manage energy conversion and motor control. SiC devices are relevant to applications that prioritize efficiency, high-voltage operation and thermal performance.
Renewable-energy systems also support demand. Solar and other power-conversion equipment rely on semiconductor devices to manage electrical energy, creating a market for substrates used in high-performance power components.
Industrial applications broaden the demand base beyond automotive. Power supplies, motor drives and other high-power electronic systems can use SiC devices where operating efficiency and electrical performance are important.
These application areas collectively support demand for qualified SiC substrates and encourage investment in wafer production capacity.
Receive your Free Sample Report today: https://semiconductorinsight.com/download-sample-report/?product_id=a7654ca733ac
The Transition from 6-Inch to 8-Inch Wafers Is Reshaping Manufacturing
Six-inch wafers currently benefit from an established manufacturing ecosystem and mature production processes. Equipment availability, process experience and customer qualification make the format an important part of existing SiC device manufacturing.
Eight-inch wafers offer a larger usable wafer area and the potential to produce more devices per manufacturing run. This can support economies of scale when crystal quality, wafer uniformity and fabrication yields are maintained.
The transition requires investment in crystal growth, wafer processing, metrology and compatible fabrication equipment. Suppliers must demonstrate consistent quality across the larger substrate diameter before customers can qualify the format for volume production.
Electric Vehicles and Renewable Energy Create Additional Demand
Electric-vehicle manufacturers use power electronics across traction inverters, onboard charging and related electrical systems. These applications support demand for semiconductor substrates capable of serving high-efficiency power devices.
Renewable-energy systems require power conversion equipment to connect generation assets with electrical loads and grids. SiC-based components can be used in selected conversion architectures where their material properties provide system-level advantages.
The report also identifies industrial sectors as relevant demand sources. Growth across these applications broadens the wafer market and reduces its dependence on a single end-use category.
Material Quality and Manufacturing Yield Remain Critical
SiC wafer production requires control over crystal quality, defects, surface condition and electrical characteristics. Variations in substrate quality can affect downstream device yield and the reliability of finished power components.
Scaling from 6-inch to 8-inch production adds manufacturing challenges because quality and uniformity must be maintained across a larger wafer area. Capacity expansion therefore depends on process maturity as well as installed equipment.
Manufacturers must balance output, yield, wafer quality and cost. Suppliers that can deliver consistent substrates and support customer qualification are positioned to participate in the industry's move toward larger wafer formats.
Access the Full Report for In-Depth Insights: https://semiconductorinsight.com/report/silicon-carbide-sic-wafer-6-inch-8-inch-market/
Economies of Scale Are an Important Market Driver
Larger wafer diameters can improve the economics of device manufacturing by increasing the potential number of dies produced in each wafer run. The benefit depends on usable wafer area, die size, defect density and downstream process yield.
Compatibility with existing semiconductor manufacturing infrastructure is another consideration. The report identifies the transition toward 8-inch formats as a strategic development as manufacturers seek to scale production and improve cost efficiency.
However, moving to larger wafers requires capital investment and technical validation. The commercial advantage becomes meaningful when production processes achieve the required levels of quality, uniformity and yield.
Where Are the Biggest Opportunities Emerging?
Eight-inch wafer manufacturing represents a major opportunity as suppliers develop the capability to serve larger-diameter SiC device production. Successful qualification can support higher device output per wafer and improved manufacturing economics.
Electric vehicles remain an important opportunity because traction inverters and charging systems require power semiconductor devices. Continued adoption of SiC in high-power electronics supports the need for qualified substrates.
Renewable-energy systems and industrial power electronics provide additional demand. These applications use power devices in conversion and control systems where efficiency and thermal performance are important.
Suppliers that combine wafer quality, manufacturing scale and customer qualification capabilities can benefit as the market moves from established 6-inch production toward 8-inch manufacturing.
Silicon Carbide (SiC) Wafer (6-inch, 8-inch) Market Segmentation
The report evaluates the market by wafer diameter and related material and application categories, with a focus on 6-inch and 8-inch formats.
By type, the market is divided into:
· 6-inch (150 mm) wafers
· 8-inch (200 mm) wafers
By application, the market covers:
· Electric vehicles (EVs)
· High-power electronics
· Renewable-energy systems
· Industrial power semiconductor applications
The supplied page also discusses wafer diameter and crystal orientation, including 150 mm and 200 mm formats and 4H-SiC and 6H-SiC. The application detail visible in the extract emphasizes EVs and high-power electronic uses.
View the complete Silicon Carbide (SiC) Wafer (6-inch, 8-inch) Market segmentation and forecast: https://semiconductorinsight.com/report/silicon-carbide-sic-wafer-6-inch-8-inch-market/
Regional Silicon Carbide (SiC) Wafer (6-inch, 8-inch) Market Outlook
Asia-Pacific is a major manufacturing and technology region for SiC wafers. The source page identifies China and Japan among the important markets and links regional activity to semiconductor manufacturing and power-device demand.
North America is an important market because of its semiconductor and power-electronics ecosystem. The report identifies the region within its global regional coverage.
Europe is included in the report’s regional analysis, with demand connected to automotive, industrial and power-electronics applications.
South America and the Middle East and Africa are also included in the global coverage. The accessible report extract does not provide a verified 2026–2034 country-level forecast for these regions.
Competitive Landscape and Key Companies
Semiconductor Insight identifies Wolfspeed, II-VI Incorporated, Soitec, SK Siltron, Norstel, Microchip Technology, Qorvo, STMicroelectronics, ROHM, Sumitomo Heavy Industries, Winbond, Infineon, ON Semiconductor, Nexperia and Epistar among the companies profiled.
Competition is shaped by wafer diameter capability, crystal quality, manufacturing yield, production capacity and the ability to qualify substrates with downstream device manufacturers. The transition toward 8-inch production is an important competitive differentiator.
Manufacturers are also assessed on research and development, pricing strategies, product offerings, capacity expansion and partnerships. The report considers competitive positioning across the SiC wafer supply chain.
What Does the Silicon Carbide (SiC) Wafer (6-inch, 8-inch) Market Report Cover?
The Semiconductor Insight study examines the SiC wafer market through market size and forecast, segmentation, regional performance, technology trends and competitive landscape.
The report covers 6-inch and 8-inch wafer formats and discusses the shift toward larger substrates, economies of scale, manufacturing yield and applications in power electronics, electric vehicles and renewable energy.
The study also profiles key manufacturers and evaluates regional market conditions, market drivers and restraints, technology developments and stakeholder opportunities.
Key Questions Answered by the Study
The report helps industry participants evaluate questions including:
· What was the SiC Wafer (6-inch, 8-inch) Market size in 2025?
· How large is the market projected to become by 2034?
· What is the expected CAGR during 2026–2034?
· Why are 6-inch wafers important to current production?
· What advantages can 8-inch wafers provide?
· Which applications are driving SiC wafer demand?
· How do electric vehicles influence the market?
· Why are crystal quality and wafer yield important?
· Which companies are profiled in the report?
· What role do 4H-SiC and 6H-SiC play?
· Which regions are covered in the market analysis?
· What are the main competitive trends in wafer manufacturing?
Explore the full Silicon Carbide (SiC) Wafer (6-inch, 8-inch) Market forecast and competitive analysis: https://semiconductorinsight.com/report/silicon-carbide-sic-wafer-6-inch-8-inch-market/
Get a Sample Report copy for free: https://semiconductorinsight.com/download-sample-report/?product_id=a7654ca733ac
About Semiconductor Insight
Semiconductor Insight provides market intelligence and industry research covering semiconductor technologies, electronic components, advanced manufacturing systems and related technology markets. Its research focuses on market sizing, forecasting, competitive landscapes, technology trends, segmentation and regional analysis to support strategic decision-making across the semiconductor ecosystem.
Contact Semiconductor Insight
Website: www.semiconductorinsight.com

 English
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
