
Electrosurgery Devices Market Expected to Reach USD 22.8 Billion by 2036, with Top Players Medtronic, J&J Ethicon and Olympus
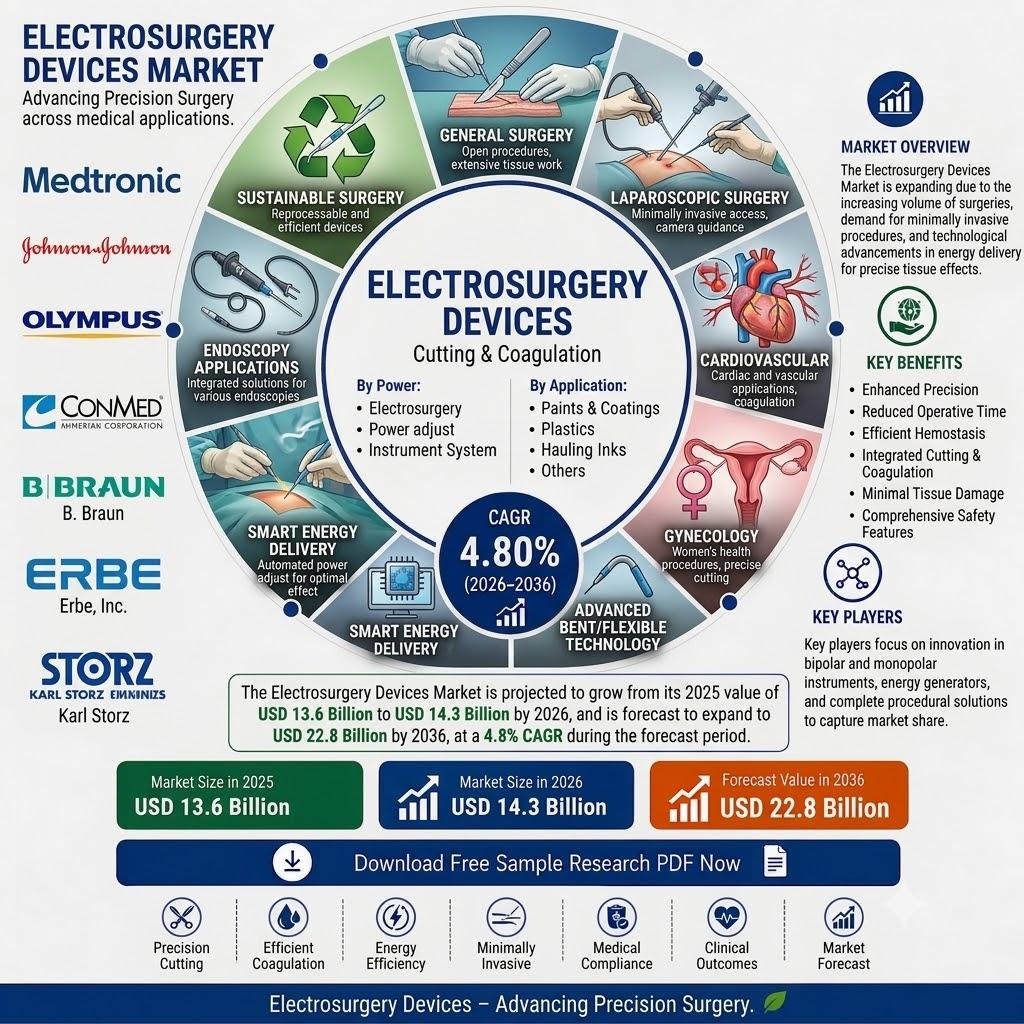
The global electrosurgery devices market is projected to grow from USD 14.3 billion in 2026 to USD 22.8 billion by 2036, registering a compound annual growth rate (CAGR) of 4.8% during the forecast period, according to Fact.MR. The market is expected to create an incremental revenue opportunity of approximately USD 8.5 billion as hospitals and ambulatory surgical centers expand their use of electrosurgical equipment across general surgery, gynecology, urology, and other specialties.
Electrosurgical devices use high-frequency electrical current to cut, coagulate, seal, and ablate tissue during surgical procedures. Their established role in operating rooms makes demand closely linked to surgical activity. Growing adoption of minimally invasive procedures and the expansion of outpatient surgical facilities are also influencing equipment procurement and replacement decisions.
Get detailed market forecasts, competitive benchmarking, and pricing trends: https://www.factmr.com/connectus/sample?flag=S&rep_id=126
Electrosurgical Generators Maintain a Leading Product Position
Electrosurgical generators account for 38% of the product segment in 2026, supported by the widespread use of monopolar and bipolar systems in hospitals and ambulatory surgical centers. Generators serve as the core equipment for electrosurgical procedures, while instruments and accessories generate recurring demand through procedure-linked purchases.
General surgery represents the leading application segment, with a 29% share in 2026. Gastrointestinal, hepatobiliary, and abdominal procedures continue to support demand for electrosurgical cutting and coagulation systems. Gynecological, urological, cardiovascular, and oncological procedures also contribute to equipment and instrument requirements.
Hospitals account for 61% of end-use demand, reflecting their concentrated surgical volumes and established operating room infrastructure. The monopolar technology segment holds a 44% share, supported by its broad installed base across surgical specialties. Direct sales represent 63% of the distribution channel, reflecting procurement relationships between medical device manufacturers and healthcare institutions.
Regional Outlook: United States Leads Country-Level Growth
The United States is projected to record the fastest country-level growth, with a CAGR of 5.2% through 2036. High surgical volumes, ambulatory surgical center expansion, and adoption of advanced energy platforms are supporting equipment demand. Each new surgical center creates requirements for generators, instruments, and ongoing consumable supplies.
Mexico follows with a projected CAGR of 4.9%, supported by hospital infrastructure investment and expanding surgical capacity. Germany is expected to grow at 4.6%, while France is projected to register 4.5%. South Korea is forecast to expand at 4.4%, with the United Kingdom and Japan each expected to record a CAGR of 4.3%.
Analyst Perspective
Fact.MR's analysis identifies ambulatory surgical center expansion as an important source of incremental demand in developed markets. New outpatient surgical facilities require generator installations and recurring instrument supplies, adding procurement opportunities beyond established hospital networks.
The report also highlights a shift toward integrated energy platforms that combine radiofrequency with ultrasonic, bipolar, or hybrid technologies. These systems can support vessel sealing and tissue dissection while encouraging healthcare providers to upgrade older equipment. Manufacturers with integrated generator and instrument portfolios are positioned to benefit from recurring consumable demand and long-term procurement relationships.
Competitive Landscape
The global electrosurgery devices market includes established medical technology companies with broad surgical equipment portfolios. Key companies profiled by Fact.MR include Medtronic plc, Johnson & Johnson (Ethicon), Olympus Corporation, ConMed Corporation, B. Braun Aesculap, Erbe Elektromedizin, Karl Storz SE & Co. KG, Stryker Corporation, Boston Scientific Corporation, and Zimmer Biomet Holdings.
Medtronic holds an estimated 34.9% market share in 2026, supported by its advanced energy platforms, hospital procurement relationships, and global distribution network. Competition is increasingly shaped by integrated product ecosystems, instrument compatibility, technology differentiation, and the ability to secure long-term hospital and ambulatory surgical center contracts.
Market Snapshot
- Market value (2026): USD 14.3 billion
- Forecast value (2036): USD 22.8 billion
- CAGR (2026–2036): 4.8%
- Incremental opportunity: Approximately USD 8.5 billion
- Leading product segment: Electrosurgical generators, with a 38% share
- Leading application: General surgery, with a 29% share
- Leading end-use segment: Hospitals, with a 61% share
- Leading company: Medtronic, with a 34.9% market share
- Fastest-growing country: United States, at a 5.2% CAGR
To View Related Reports
https://www.blogger.com/blog/post/preview/8852343521825395046/6630885539947762816
https://sportgalax.com/read-blog/26883
About Fact.MR
Fact.MR is a market research and competitive intelligence provider delivering market intelligence, competitive analysis, and forecasting across global industries. Its research helps businesses evaluate market demand, understand competitive developments, and identify growth opportunities.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Romaian
 Portuguese (Brazil)
 Greek
