Heparin Market Developments in Ultra-Low Molecular Weight Heparin
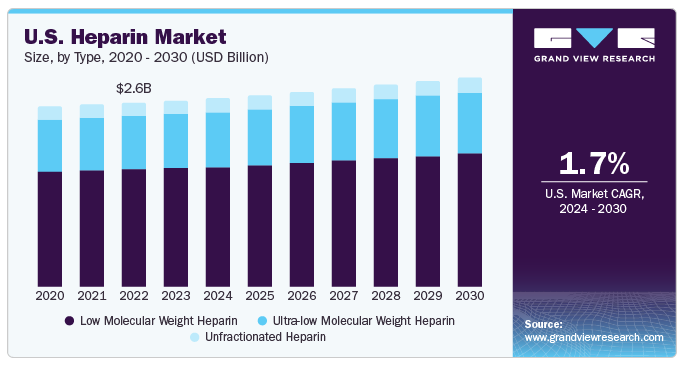
The global heparin market is experiencing steady growth as healthcare systems respond to the rising burden of cardiovascular diseases, increasing demand for blood transfusions, and expanding medical needs among older populations. Heparin Market Valued at USD 7.6 billion in 2023, the market is projected to grow from USD 8.1 billion in 2026 to USD 9.0 billion by 2030, registering a CAGR of 2.7% from 2024 to 2030. As an anticoagulant used to prevent and manage blood clot formation, heparin remains important in cardiovascular care, surgical procedures, and the prevention of venous thromboembolism. North America led the market with a 38.6% revenue share in 2023, while continued healthcare investment and evolving treatment requirements are expected to sustain demand.
Heparin Market at a Glance
Market value: USD 7.6 billion in 2023
Projected value: USD 9.0 billion by 2030
Forecast CAGR: 2.7% from 2024 to 2030
Leading product type: Low Molecular Weight Heparin, with a 63.7% share in 2023
Leading application: Coronary Artery Disease, accounting for 23.4% in 2023
Dominant administration route: Subcutaneous, with a 65.4% share in 2023
What Is Driving Demand for Heparin?
The increasing prevalence of chronic diseases is a major factor supporting the heparin market. Cardiovascular conditions often require anticoagulant therapy to reduce the risk of blood clot formation during treatment and medical procedures. According to the World Health Organization figures cited in the supplied market information, noncommunicable diseases caused approximately 41 million deaths annually, including 17.9 million attributed to cardiovascular diseases. This substantial disease burden reinforces the need for effective anticoagulant therapies.
Growing demand for whole blood and blood component transfusions is another contributor. Heparin is used in specific medical and laboratory settings involving blood management, making reliable supply and appropriate clinical use important considerations. Meanwhile, population aging is increasing the number of people requiring medical interventions associated with clot prevention.
The pharmaceutical industry's use of plasma-derived products also supports market demand. Investments in manufacturing facilities and treatment production capacity highlight the continuing need for materials and medicines used across specialized healthcare applications.
Want to Understand What’s Driving Market Growth? Ask Prism AI for research-backed insights into market size, evolving opportunities
Which Heparin Types Are Gaining Market Attention?
Low Molecular Weight Heparin (LMWH) dominated the market, accounting for 63.7% of revenue in 2023. Products such as enoxaparin and dalteparin are used in preventing and treating thromboembolic conditions, including deep vein thrombosis and pulmonary embolism. LMWH is widely used because of its established role in anticoagulant therapy and its suitability for subcutaneous administration in appropriate clinical settings.
Ultra-Low Molecular Weight Heparin (ULMWH) is expected to register the fastest growth among the product types covered in the report. These compounds have a lower molecular weight and act through anticoagulant pathways involving antithrombin. Their potential applications in preventing venous thromboembolism among selected patient groups are attracting attention. However, bleeding, allergic reactions, and heparin-induced thrombocytopenia remain important safety considerations in anticoagulant treatment.
Why Is Coronary Artery Disease a Leading Application?
Coronary Artery Disease (CAD) accounted for 23.4% of market revenue in 2023. The condition involves narrowing of the arteries supplying blood to the heart and can lead to serious cardiovascular complications. Heparin plays a role in selected acute coronary care and medical procedures by helping prevent blood clot formation.
Atrial fibrillation is another application area expected to experience significant growth during the forecast period. The heart rhythm disorder can increase the risk of blood clots and stroke, creating demand for appropriate anticoagulation strategies. The report cites an estimate that atrial fibrillation could affect 12.1 million people in the United States by 2030. Treatment decisions depend on individual clinical circumstances, and heparin is used in specific settings rather than as the standard long-term therapy for every patient with atrial fibrillation.
Download a free sample report or claim your copy of this full market intelligence report
How Are Administration Routes Influencing Market Demand?
Subcutaneous administration represented 65.4% of heparin market revenue in 2023. Its established role in appropriate treatment settings and the ability to administer certain formulations outside hospitals contribute to its leading position. Enoxaparin, for example, has high bioavailability following subcutaneous administration, supporting its use in selected clinical applications.
Intravenous administration remains important when a rapid anticoagulant effect and close clinical control are required. Hospitals may use this route during emergencies, surgery, and other acute medical situations. The choice between administration routes depends on the formulation, indication, patient condition, and healthcare professional's assessment.
Which End-Use and Source Segments Stand Out?
Outpatient settings accounted for 61.1% of market revenue in 2023. The segment benefits from the broader shift toward cost-effective healthcare delivery, greater treatment accessibility, and care that does not require hospital admission. Inpatient demand is also expected to grow as hospitals continue managing complex cardiovascular conditions, surgeries, and other situations requiring supervised anticoagulation.
By source, porcine-derived heparin held a dominant 90.0% revenue share in 2023. Its established role in heparin production, particularly LMWH manufacturing, supports its market position. Bovine-derived heparin is projected to register the fastest growth among source segments, although differences in efficacy, pharmacological properties, manufacturing practices, and regulatory requirements remain relevant to its adoption.
Where Are the Key Regional Opportunities?
North America led the global heparin market with a 38.6% revenue share in 2023. Its position is supported by a substantial cardiovascular disease burden, established healthcare infrastructure, patient awareness, and the presence of pharmaceutical manufacturers. The United States is an important contributor to regional demand.
Asia Pacific is anticipated to register the fastest CAGR from 2024 to 2030. Cardiovascular disease prevalence, expanding healthcare requirements, and increasing demand for treatment across large patient populations are contributing to the region's growth potential. The supplied report cites approximately 330 million people in China living with cardiovascular conditions, underscoring the scale of regional healthcare needs.
What Is Shaping Competition in the Heparin Market?
Competition is influenced by product quality, manufacturing capacity, regulatory compliance, and the development of improved formulations. Manufacturers are investing in purification technologies, quality assurance, clinical trials, and regulatory submissions. Product development includes low molecular weight formulations and convenient dosage formats such as prefilled syringes.
Companies identified in the supplied report include Pfizer Inc., LEO Pharma A/S, Sanofi, Dr. Reddy’s Laboratories Ltd., GlaxoSmithKline plc, B. Braun Medical, Inc., Sandoz, and Aspen Holdings. Merger and acquisition activity can also help companies expand geographic reach and enter additional markets.
What Is the Outlook for the Heparin Market Through 2030?
The heparin market is expected to maintain steady growth as cardiovascular disease management, blood transfusion requirements, and healthcare needs among aging populations continue to support demand. LMWH, coronary artery disease treatment, and subcutaneous administration remain important components of the current market landscape, while ULMWH and Asia Pacific represent notable growth opportunities.
Although the projected CAGR of 2.7% indicates measured expansion rather than rapid acceleration, advances in formulations, manufacturing processes, and healthcare delivery may influence future market development. Continued attention to product safety, supply reliability, and clinical requirements will remain essential as heparin maintains its role in anticoagulant care.
Explore Our Research & Intelligence Solutions
U.S. Healthcare Facility Intelligence: Make Better Decisions with Comprehensive Data – Explore the Platform

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Portuguese (Brazil)
 Greek