Minimally Invasive Surgical Instruments Industry Trends, Market Demand & Growth Opportunities 2026–2034
Minimally Invasive Surgical Instruments Market Trends, Demand, Growth & Future Outlook 2026–2034
Minimally Invasive Surgical Instruments Market Size
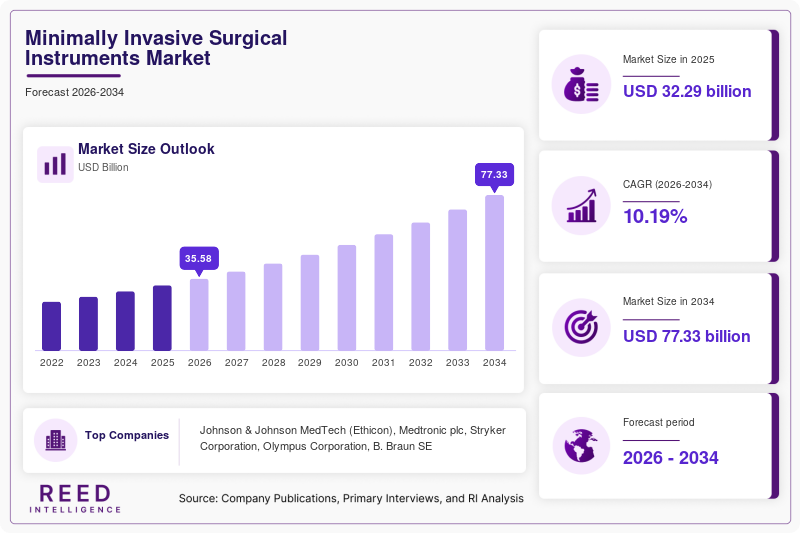
The global Minimally Invasive Surgical Instruments Market was valued at USD 32.29 billion in 2025 and is projected to grow from USD 35.58 billion in 2026 to USD 77.33 billion by 2034, registering a compound annual growth rate (CAGR) of 10.19% during the forecast period from 2026 to 2034.
The market comprises specialized medical devices used to perform surgical procedures through small incisions or natural body openings. These instruments support laparoscopic, endoscopic, arthroscopic, and other minimally invasive procedures, helping surgeons access anatomical structures while limiting unnecessary tissue disruption. Major product categories include handheld instruments, electrosurgical devices, guiding devices, inflation systems, cutters, trocars, and other procedure-specific instruments.
Market growth is supported by the increasing preference for surgical techniques that can reduce tissue trauma, postoperative discomfort, hospital stays, and recovery time when clinically appropriate. Advances in surgical visualization, instrument articulation, energy delivery, tissue sealing, and robotic-assisted platforms are expanding the range of procedures performed using minimally invasive techniques. These developments encourage healthcare providers to upgrade surgical equipment and improve operating-room capabilities.
Key Takeaways
-
Market Size (2026): USD 35.58 billion.
-
Market Size Forecast (2034): USD 77.33 billion.
-
CAGR (2026–2034): 10.19%.
-
Leading Product Category: Handheld instruments are identified as a leading category in the supplied market information; a verified market share is not available.
-
Dominant Application: Orthopedic surgery is identified as a leading application in one published estimate, although a comparable market share is not provided.
-
Dominant Region: North America, with a reported 38.2% share in 2025 from a third-party report covering a broader market scope.
-
Key Market Drivers: Increasing preference for minimally invasive procedures and technological advancements in surgical instruments.
-
Major Restraints: High acquisition and maintenance costs, training requirements, and procedural complexity.
-
Emerging Opportunities: Expansion of ambulatory surgery and growth in robotic-assisted and advanced energy technologies.
Minimally Invasive Surgical Instruments Market Trends
The Minimally Invasive Surgical Instruments Market is evolving alongside advances in surgical technology and the increasing use of procedures designed to limit tissue disruption. Developments in high-definition visualization, instrument articulation, energy delivery, and tissue sealing are helping surgeons perform increasingly complex procedures through smaller access points.
Manufacturers are focusing on precision, ergonomics, reliable tissue handling, and compatibility with advanced surgical platforms. Articulating instruments, advanced staplers, and energy-based devices are important product-development areas because they can support surgical work in restricted anatomical spaces.
Robotic-assisted surgery is another relevant technology trend, creating opportunities for specialized instruments designed to work with surgical platforms. At the same time, healthcare providers are evaluating equipment costs, training requirements, instrument reliability, and operating-room efficiency when selecting new technologies.
The expansion of ambulatory surgical centers and outpatient procedures is also influencing purchasing priorities. Facilities may favor reliable, procedure-specific instrument sets that support predictable costs, efficient workflows, and appropriate sterilization processes.
Minimally Invasive Surgical Instruments Market Drivers
Increasing Preference for Minimally Invasive Procedures
Patients and healthcare providers increasingly consider minimally invasive approaches when they offer suitable clinical benefits. Smaller incisions and reduced disruption of surrounding tissue can support recovery and may reduce postoperative complications in appropriate cases.
Growing adoption across general surgery, gynecology, urology, orthopedics, and gastrointestinal surgery creates demand for specialized instruments, visualization systems, cutting tools, and tissue-sealing technologies. As healthcare providers expand their minimally invasive capabilities, demand for procedure-specific devices can increase.
Technological Advancements in Surgical Instruments
Innovation in instrument design, energy-based devices, high-definition visualization, and robotic-assisted surgery is expanding the capabilities available to surgeons. Articulating instruments, advanced staplers, and energy devices can support complex procedures in restricted anatomical spaces.
Manufacturers are emphasizing ergonomics, precision, dependable tissue handling, and integration with surgical platforms. These improvements can help healthcare providers enhance procedural efficiency and expand the range of minimally invasive interventions they can perform.
Minimally Invasive Surgical Instruments Market Restraints
High Acquisition and Maintenance Costs
Advanced surgical instruments may require substantial investment in equipment, compatible accessories, sterilization infrastructure, maintenance, and staff training. Robotic-compatible and energy-based systems can add further expenses for healthcare providers.
These costs may limit adoption among smaller hospitals, facilities in lower-income markets, and institutions with restricted capital budgets. Procurement decisions therefore depend on procedure volumes, expected clinical value, equipment utilization, and available funding.
Training Requirements and Procedural Complexity
Minimally invasive surgery requires specialized skills in instrument handling, visualization, navigation, and coordination. Surgeons and operating-room teams may need structured training and supervised experience before adopting new devices or techniques.
Differences in clinical expertise and access to simulation facilities can slow implementation. Reusable instruments also require appropriate cleaning, inspection, and sterilization, while disposable instruments create recurring procurement costs and waste-management considerations.
Minimally Invasive Surgical Instruments Market Opportunities
Expansion of Ambulatory and Outpatient Surgery
The development of ambulatory surgical centers and outpatient procedure programs creates opportunities for minimally invasive instrument suppliers. When clinically appropriate, minimally invasive techniques can support shorter recovery periods and efficient use of healthcare resources.
Providers that develop reliable, procedure-specific instrument sets and simplified workflows may benefit from demand among facilities seeking to improve operating-room utilization and deliver selected procedures outside traditional inpatient settings.
Growth of Robotic-Assisted and Advanced Energy Technologies
Robotic-assisted procedures, advanced stapling, electrosurgical instruments, and improved surgical visualization create opportunities for differentiated product development. Manufacturers can strengthen their portfolios by improving instrument precision, articulation, energy control, and compatibility with surgical platforms.
Continued investment in surgeon education, clinical evidence, and connected operating-room technologies may support adoption, particularly in hospitals expanding complex minimally invasive surgery programs.
Minimally Invasive Surgical Instruments Market Segmentation Analysis
By Product Type
The market includes handheld instruments, electrosurgical devices, guiding devices, cutter instruments, inflation devices, and other instruments.
Handheld instruments allow surgeons to grasp, dissect, manipulate, cut, and suture tissue through small access points. This category includes forceps, graspers, scissors, needle holders, and related tools. Electrosurgical devices deliver energy for cutting, coagulation, and tissue sealing, while guiding devices, inflation systems, cutters, and other instruments perform specialized functions within procedure-specific workflows.
The supplied market information identifies handheld instruments as a leading product category, reflecting their broad use across surgical specialties. Electrosurgical devices are also expected to benefit from demand for efficient cutting and hemostasis. However, a verified leading-segment share and fastest-growing product CAGR are not available for the precise market definition used in the report.
By Application
The market is segmented into orthopedic surgery, cardiovascular surgery, gastrointestinal surgery, gynecological surgery, urological surgery, and other applications.
Orthopedic procedures may rely on arthroscopic instruments, while gastrointestinal and gynecological procedures often use laparoscopic instruments, access devices, cutters, and energy-based tools. Cardiovascular and urological procedures may require specialized instruments designed for anatomical access and precise intervention.
Demand across applications depends on procedure volumes, clinical suitability, specialist availability, and the adoption of minimally invasive techniques. Orthopedic surgery is identified as a leading application in one published estimate, while gastrointestinal and cardiothoracic procedures are cited among growth opportunities in another estimate. The supplied information does not establish comparable market shares or growth rates for all applications.
By End User
End users include hospitals, ambulatory surgical centers, specialty clinics, and other healthcare facilities.
Hospitals are important purchasers because they provide multidisciplinary surgical services, manage complex cases, and maintain operating rooms equipped for a wide range of procedures. Their requirements include reusable and single-use instruments, electrosurgical equipment, access devices, cutters, and procedure-specific tool sets.
Large hospitals and specialist centers may also invest in advanced technologies supporting complex laparoscopic and robotic-assisted surgery. Ambulatory surgical centers represent an additional opportunity as selected procedures move toward outpatient settings. These facilities may prioritize reliable instruments, predictable procedure costs, efficient turnover, and appropriate sterilization workflows.
Minimally Invasive Surgical Instruments Market Regional Analysis
North America Minimally Invasive Surgical Instruments Market
North America dominated the market in 2025, accounting for an estimated 38.2% of global revenue according to Dataintelo's report on the broader minimally invasive surgical instruments and accessories market. This is a third-party estimate from a related market scope and is not a verified share specific to the USD 32.29 billion valuation used in this report.
The region's position is supported by advanced healthcare infrastructure, high surgical procedure volumes, established reimbursement systems, and widespread adoption of laparoscopic, endoscopic, and robotic-assisted technologies. The United States is a major contributor to regional demand, supported by investments in advanced surgical equipment and the presence of leading medical-device manufacturers.
Europe Minimally Invasive Surgical Instruments Market
Europe represents an established market supported by advanced hospital infrastructure, specialist surgical centers, and widespread use of laparoscopic and endoscopic procedures. Germany, France, the United Kingdom, Italy, and other European countries contribute to regional demand for handheld instruments, electrosurgical devices, cutters, and specialized surgical tools.
Product safety, regulatory compliance, clinical performance, and procurement requirements influence competition among manufacturers. Continued adoption of advanced surgical technologies and the need for reliable procedure-specific instruments remain relevant considerations for suppliers.
Asia Pacific Minimally Invasive Surgical Instruments Market
Asia Pacific offers growth opportunities as healthcare infrastructure expands and hospitals increase their capacity to perform minimally invasive procedures. China, Japan, India, South Korea, and Australia are important markets, with demand influenced by healthcare spending, specialist availability, hospital modernization, and adoption of advanced surgical technologies.
Greater access to surgical care and the development of specialist facilities may support demand for procedure-specific instruments. Market development will vary according to healthcare investment, clinical training capacity, equipment affordability, and access to advanced surgical platforms.
Latin America Minimally Invasive Surgical Instruments Market
Latin America presents opportunities as hospitals and surgical centers modernize operating rooms and expand minimally invasive procedures. Brazil and Mexico are important regional markets, while other countries contribute through private hospitals, specialist clinics, and developing surgical infrastructure.
Demand spans instruments used in general surgery, gynecology, orthopedics, urology, and other specialties. Market development depends on healthcare funding, procurement priorities, access to trained professionals, and the availability of appropriate surgical equipment.
Middle East & Africa Minimally Invasive Surgical Instruments Market
The Middle East and Africa market is influenced by investment in tertiary-care hospitals, specialist surgical centers, and healthcare modernization. Some Gulf countries are expanding advanced surgical capabilities, while demand in other markets depends on healthcare funding, infrastructure availability, and access to trained surgical professionals.
These factors influence purchasing decisions for handheld instruments, electrosurgical devices, and specialized minimally invasive tools. Suppliers must account for differences in healthcare infrastructure, procurement capacity, and access to advanced surgical services across the region.
Minimally Invasive Surgical Instruments Market Competitive Landscape
The market includes multinational medical-device companies and specialist manufacturers supplying instruments for laparoscopic, endoscopic, arthroscopic, and other minimally invasive procedures. Competition is based on instrument reliability, ergonomic design, precision, advanced energy delivery, product breadth, clinical evidence, regulatory compliance, and distribution capabilities.
Johnson & Johnson MedTech (Ethicon) is a significant participant in surgical instruments, stapling, energy-based devices, and related surgical technologies. Its portfolio includes instruments designed for open, laparoscopic, and robotic-assisted procedures. Product development emphasizes tissue handling, staple-line integrity, usability, and integration with evolving surgical platforms.
Other major participants include Medtronic, Stryker, Olympus, B. Braun, Smith & Nephew, CONMED, Zimmer Biomet, Karl Storz, and Richard Wolf. Their participation reflects the range of products and specialized technologies used across surgical procedures and healthcare settings.
Key Market Players
The key companies identified in the supplied market information include:
-
Johnson & Johnson MedTech (Ethicon)
-
Medtronic plc
-
Stryker Corporation
-
Olympus Corporation
-
B. Braun SE
-
Smith & Nephew plc
-
CONMED Corporation
-
Zimmer Biomet Holdings, Inc.
-
Karl Storz SE & Co. KG
-
Richard Wolf GmbH
Minimally Invasive Surgical Instruments Market Recent Developments
April 2026 – Johnson & Johnson Receives CE Mark Approval for the ETHICON 4000 Stapler
Johnson & Johnson announced European approval for the ETHICON 4000 Stapler and ETHICON 3D Reloads for use in open and laparoscopic surgery across specialties in the European Union. The system incorporates 3D stapling technology and enhanced gripping-surface technology intended to support staple-line integrity across different tissue thicknesses.
The development highlights continued product innovation in surgical stapling and technologies designed for use across different tissue conditions.
June 2026 – Stryker Launches the TPX HD Power Tool
Stryker announced the launch of its TPX HD small-bone power tool for demanding orthopedic procedures, including minimally invasive surgery and oral and maxillofacial procedures. The design emphasizes visibility in confined spaces, control, and ergonomics.
The launch illustrates ongoing development of specialized surgical tools intended to address the requirements of procedures performed in anatomically restricted areas.
Minimally Invasive Surgical Instruments Market Segments
By Product Type
-
Handheld Instruments
-
Electrosurgical Devices
-
Guiding Devices
-
Cutter Instruments
-
Inflation Devices
-
Other Instruments
By Application
-
Orthopedic Surgery
-
Cardiovascular Surgery
-
Gastrointestinal Surgery
-
Gynecological Surgery
-
Urological Surgery
-
Other Applications
By End User
-
Hospitals
-
Ambulatory Surgical Centers
-
Specialty Clinics
-
Other End Users
By Region
-
North America
-
Europe
-
Asia Pacific
-
Middle East and Africa
-
Latin America
Frequently Asked Questions
What is the size of the Minimally Invasive Surgical Instruments Market?
The global market was valued at USD 32.29 billion in 2025. It is projected to reach USD 35.58 billion in 2026 and USD 77.33 billion by 2034, registering a CAGR of 10.19% during 2026–2034.
What factors are driving the Minimally Invasive Surgical Instruments Market?
Key drivers include increasing preference for minimally invasive procedures and technological advancements in surgical instruments. Improvements in visualization, instrument articulation, energy delivery, and robotic-assisted surgery are also supporting market development.
Which products are included in the Minimally Invasive Surgical Instruments Market?
The market includes handheld instruments, electrosurgical devices, guiding devices, cutter instruments, inflation devices, and other procedure-specific instruments.
Which region dominates the Minimally Invasive Surgical Instruments Market?
North America is identified as the dominant region in the supplied information, with a third-party estimate of 38.2% of global revenue in 2025. This estimate refers to a broader related market scope and should not be treated as a verified share of the exact market valuation used in this report.
Who are the key players in the Minimally Invasive Surgical Instruments Market?
Key players include Johnson & Johnson MedTech (Ethicon), Medtronic plc, Stryker Corporation, Olympus Corporation, B. Braun SE, Smith & Nephew plc, CONMED Corporation, Zimmer Biomet Holdings, Inc., Karl Storz SE & Co. KG, and Richard Wolf GmbH.
Conclusion
The Minimally Invasive Surgical Instruments Market is projected to grow from USD 35.58 billion in 2026 to USD 77.33 billion by 2034, registering a CAGR of 10.19%. Increasing preference for minimally invasive procedures, advances in surgical technologies, and expanding outpatient surgery capabilities are important factors supporting the market outlook.
However, high equipment costs, maintenance requirements, and the need for specialized surgical training can limit adoption. Opportunities exist in robotic-assisted surgery, advanced energy technologies, procedure-specific instruments, and the expansion of ambulatory surgical centers. Manufacturers that prioritize precision, reliability, clinical performance, and compatibility with evolving surgical platforms may be well positioned to address changing healthcare needs.
Full Report URL: https://reedintelligence.com/market-analysis/minimally-invasive-surgical-instruments-market

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek