
Compliance Software Market Trends 2026: Automation, Risk Management & Regulatory Innovation
I’ve reviewed the uploaded Compliance Software Market source and will use it as the sole basis for the report, preserving its figures, segmentation, and terminology.
Compliance Software Market Trends, Demand, Growth & Future Outlook 2026–2034
Compliance Software Market Size
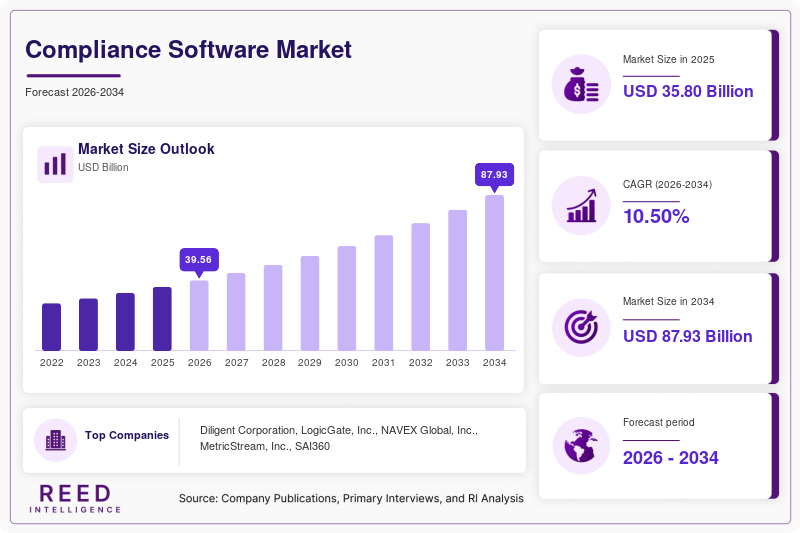
The global Compliance Software Market was valued at USD 35.80 billion in 2025 and is projected to grow from USD 35.80 billion in 2026 to USD 87.93 billion by 2034, registering a CAGR of 10.50% during the forecast period from 2026 to 2034.
The market is increasingly organized around continuous compliance rather than periodic compliance exercises. Modern platforms centralize regulatory requirements, policies, controls, assessments, evidence, and reporting, allowing compliance teams to maintain a persistent view of control effectiveness. Regulatory complexity is also increasing demand for workflow automation and centralized regulatory intelligence across highly regulated industries.
Key Takeaways
-
The market is projected to reach USD 87.93 billion by 2034 from USD 35.80 billion in 2026.
-
The market is expected to register a 10.50% CAGR during 2026–2034.
-
Software accounted for an estimated 74.0% share in 2026.
-
Regulatory Compliance accounted for an estimated 31.0% share in 2026.
-
Data Privacy & Security Compliance is projected to be the fastest-growing application, with a 12.0% CAGR.
-
Cloud deployment accounted for an estimated 68.0% share in 2026.
-
North America is the dominant region, with an estimated 36.0% share in 2026.
-
Asia Pacific is projected to be the fastest-growing regional market, with a 12.4% CAGR.
-
AI governance, continuous compliance monitoring, cloud deployment, and product compliance are creating new market opportunities.
Request Sample
https://reedintelligence.com/market-analysis/compliance-software-market/request-sample
Compliance Software Market Trends
Continuous Compliance Monitoring Is Replacing Periodic Compliance Processes
Organizations are increasingly moving away from spreadsheets, manual evidence collection, email-based approvals, and periodic audits toward continuous compliance platforms. These systems centralize requirements, policies, controls, assessments, evidence, and reporting, helping organizations maintain ongoing visibility into control effectiveness.
AI Is Turning Compliance Platforms Into Active Workflow Systems
AI is expanding the role of compliance software by enabling analysis of regulatory, operational, and risk information. AI-enabled platforms can help identify missing evidence, classify obligations, summarize information, and prioritize activities for human review.
KPMG's 2026 Global Chief Ethics and Compliance Officer Survey found that 68% of surveyed CCOs had a mixed-to-positive view of AI use, while 50% reported using AI for compliance risk assessment and management.
Cloud Deployment Is Changing Compliance Technology Economics
Cloud-based compliance software allows organizations to centralize regulatory content, workflows, evidence, and reporting without maintaining equivalent on-premises infrastructure. Cloud deployment also enables vendors to release regulatory updates and platform improvements centrally.
However, sensitive compliance information makes security, data residency, access control, and vendor-risk assessment important purchasing considerations.
Compliance Software Market Drivers
Increasing Regulatory Complexity
Organizations increasingly operate under multiple frameworks covering privacy, cybersecurity, financial reporting, financial crime, workplace requirements, sustainability, and operational resilience. This increases the volume of evidence, documentation, and control testing required by compliance teams.
PwC's 2025 global compliance research found that 82% of companies planned to invest more in at least one technology to automate or optimize compliance activities.
AI-Driven Compliance Automation
AI is expanding compliance platforms from repositories and workflow tools into systems capable of analyzing large volumes of information and prioritizing compliance activities. Organizations can use AI to connect unstructured information with existing controls and workflows while maintaining human review for material decisions.
Growing Cloud Adoption
Cloud deployment supports subscription-based purchasing, centralized regulatory updates, and integration with cloud ERP, HR, cybersecurity, and identity systems. This makes compliance technology accessible to organizations that do not want to maintain large internal software infrastructures.
Compliance Software Market Restraints
Integration Complexity
Compliance software must connect with ERP, HR, financial, cybersecurity, identity, and operational platforms that contain underlying compliance evidence. Multiple business units and acquired companies with different technology environments can increase data-mapping, control-rationalization, and workflow-redesign requirements.
AI Governance and Data Quality Requirements
AI-enabled compliance requires reliable source data, clearly defined controls, and governance around model outputs. Poor-quality data can lead to incomplete risk assessments or incorrect classifications, while opaque AI decisions can create difficulties during internal or regulatory reviews.
Gartner estimated that fragmented AI regulation could extend across 75% of the world's economies by 2030 and projected AI-governance compliance spending to exceed USD 1 billion by that year.
Compliance Software Market Opportunities
AI Governance Is Creating a New Compliance Software Category
The expansion of AI regulation is creating compliance requirements around AI inventories, risk classification, model governance, transparency, documentation, and continuous monitoring.
Gartner's 2026 research estimates AI-governance spending at USD 492 million in 2026, with spending projected to exceed USD 1 billion by 2030.
This creates an opportunity for GRC vendors to extend existing platforms into AI governance and manage AI risks alongside privacy, cybersecurity, third-party risk, and enterprise controls.
Product Compliance and Supply-Chain Regulation
Manufacturers increasingly need to track product composition, supplier information, sustainability attributes, and regulatory obligations throughout product lifecycles. Digital Product Passport requirements and expanding product-stewardship rules are creating additional compliance data requirements.
Assent's July 2026 acquisition of IPOINT combined AI-powered product compliance, lifecycle assessment, and product intelligence capabilities intended to support Digital Product Passports and evolving regulatory requirements.
Compliance Software Market Segmental Analysis
By Component
Software
Software accounted for an estimated 74.0% share in 2026, making it the dominant component. Compliance software provides infrastructure for regulatory tracking, control management, risk assessments, evidence collection, audit workflows, reporting, and monitoring.
Software is estimated to expand at an 11.0% CAGR. Its growth is supported by the replacement of disconnected spreadsheets and manually maintained compliance repositories with centralized platforms.
Services
Services account for an estimated 26.0% share and are projected to grow at a 9.1% CAGR. Implementation, integration, consulting, managed compliance, and training remain important because organizations frequently need support configuring compliance platforms around regulatory obligations, controls, risk taxonomies, and reporting requirements.
By Application
Regulatory Compliance
Regulatory Compliance accounted for an estimated 31.0% share in 2026, making it the largest application segment. Platforms help organizations maintain regulatory requirements, map obligations to controls, assign responsibilities, collect evidence, and demonstrate compliance during audits or regulatory reviews.
Regulatory Compliance is estimated to grow at an 11.2% CAGR.
Risk Management
Risk Management accounts for an estimated 24.0% share and grows at a 10.8% CAGR. Its importance is supported by the increasing overlap between compliance data and enterprise risk programs.
Audit & Reporting
Audit & Reporting represents approximately 18.0% share and is projected to grow at a 9.7% CAGR. Centralized evidence and automated reporting support the segment's demand.
Data Privacy & Security Compliance
Data Privacy & Security Compliance accounts for approximately 17.0% share and is projected to be the fastest-growing application, with a 12.0% CAGR during the forecast period.
The convergence of privacy and cybersecurity regulation is creating demand for software capable of maintaining evidence across multiple control frameworks. AI adoption further increases demand for visibility into how sensitive data is used by AI applications and models.
Others
Other applications account for an estimated 10.0% share and grow at an 8.4% CAGR.
By Deployment
Cloud
Cloud deployment accounted for an estimated 68.0% share in 2026, making it the dominant deployment model. Cloud platforms allow vendors to update regulatory content, workflows, security capabilities, and integrations without requiring customers to maintain equivalent infrastructure.
Cloud deployment is estimated to grow at a 12.1% CAGR.
On-Premises
On-Premises deployment represents approximately 32.0% share and grows at a 6.8% CAGR. It remains relevant for organizations with strict data-residency, security, or legacy-infrastructure requirements.
Compliance Software Market Regional Analysis
North America Compliance Software Market
North America is the dominant regional market, accounting for an estimated 36.0% share in 2026. The region benefits from mature enterprise software adoption, extensive regulatory requirements, established GRC providers, and strong investment in cybersecurity, privacy, and risk management.
The United States represents the largest demand center, with financial services, healthcare, technology, government contractors, and other industries operating under complex compliance frameworks.
Europe Compliance Software Market
Europe is projected to register a 9.8% CAGR during 2026–2034. Demand is supported by extensive privacy, cybersecurity, operational-resilience, sustainability, and financial regulations across the European Union and individual jurisdictions.
AI governance is creating an additional compliance workload, while regulatory fragmentation remains an important market consideration.
Asia Pacific Compliance Software Market
Asia Pacific is projected to be the fastest-growing regional market, with a 12.4% CAGR. Adoption is supported by digital transformation, expanding financial and technology sectors, cloud migration, and increasing data-protection and cybersecurity requirements.
China, Japan, India, South Korea, Singapore, and Australia represent important demand centers. Cloud-native compliance vendors can address opportunities among newer digital businesses that do not have extensive legacy compliance infrastructures.
Middle East & Africa Compliance Software Market
Middle East & Africa is projected to grow at an 11.3% CAGR through 2034. Digital-government programs, financial-sector modernization, cybersecurity investment, and expansion of regulated industries are creating demand for automated compliance management.
Financial institutions represent an important customer group because their compliance processes involve regulatory reporting, customer due diligence, transaction monitoring, and risk assessment.
Latin America Compliance Software Market
Latin America is projected to register a 10.7% CAGR during 2026–2034. Demand is supported by financial-sector regulation, digital banking, data-protection requirements, cybersecurity programs, and cloud enterprise software adoption.
Brazil and Mexico represent major enterprise technology markets, while cloud-based and managed compliance solutions provide opportunities for organizations with limited internal infrastructure and specialist personnel.
Competitive Landscape
The Compliance Software Market is moderately fragmented across large enterprise software providers, dedicated GRC vendors, RegTech companies, cybersecurity providers, and specialized compliance platforms. Competitive differentiation increasingly centers on workflow automation, regulatory intelligence, AI capabilities, integrations, and breadth of risk and compliance functions.
Diligent is a major GRC platform provider with capabilities across governance, risk, audit, compliance, and board management. Its 2026 product development has focused on agentic AI, including AI agents embedded across Diligent One and AI-powered cyber-risk management.
Key Market Players
-
Diligent Corporation
-
LogicGate, Inc.
-
NAVEX Global, Inc.
-
MetricStream, Inc.
-
SAI360
-
SAP SE
-
ServiceNow, Inc.
-
IBM Corporation
-
OneTrust Technology Limited
-
Thomson Reuters Corporation
-
ComplyAdvantage
-
Assent Inc.
-
VComply
-
RSA Security LLC
-
Wolters Kluwer N.V.
Compliance Software Market Recent Developments
-
September 2026: Diligent announced new agentic capabilities in Diligent One designed to connect fragmented GRC information, surface relevant issues, and accelerate execution while retaining human governance and professional judgment.
-
July 2026: Assent completed its acquisition of IPOINT, combining AI, product-compliance data, and lifecycle expertise. The transaction expands capabilities around product intelligence, product stewardship, and Digital Product Passport requirements.
Compliance Software Market Segments
By Component
-
Software
-
Services
By Application
-
Regulatory Compliance
-
Risk Management
-
Audit & Reporting
-
Data Privacy & Security Compliance
-
Others
By Deployment
-
Cloud
-
On-Premises
By Region
-
North America
-
Europe
-
APAC
-
Middle East and Africa
-
LATAM
Frequently Asked Questions
What is the size of the Compliance Software Market in 2026?
The global Compliance Software Market is valued at USD 35.80 billion in 2026.
What will the Compliance Software Market size be in 2034?
The Compliance Software Market is projected to reach USD 87.93 billion by 2034.
What is the CAGR of the Compliance Software Market from 2026 to 2034?
The market is projected to register a CAGR of 10.50% during 2026–2034.
Which application dominates the Compliance Software Market?
Regulatory Compliance is the largest application segment, accounting for an estimated 31.0% share in 2026.
Which region is expected to grow fastest in the Compliance Software Market?
Asia Pacific is projected to be the fastest-growing regional market, with a 12.4% CAGR.
Conclusion
The Compliance Software Market is expanding as organizations shift from periodic compliance exercises toward continuous monitoring, centralized control management, automated evidence collection, and digital regulatory workflows. Increasing regulatory complexity, AI adoption, cloud deployment, and the emergence of AI governance and product-compliance requirements are expanding the role of compliance platforms.
The market is projected to increase from USD 35.80 billion in 2026 to USD 87.93 billion by 2034 at a CAGR of 10.50%. Software remains the dominant component, Regulatory Compliance is the largest application, Cloud is the leading deployment model, and North America holds the largest regional share. Asia Pacific is projected to record the fastest regional growth, while Data Privacy & Security Compliance represents the fastest-growing application segment.
Report URL
https://reedintelligence.com/market-analysis/compliance-software-market

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Romaian
 Portuguese (Brazil)
 Greek
