
United States Wireless IoT Connectivity Market Report: Growth & Future Outlook (2025–2031)
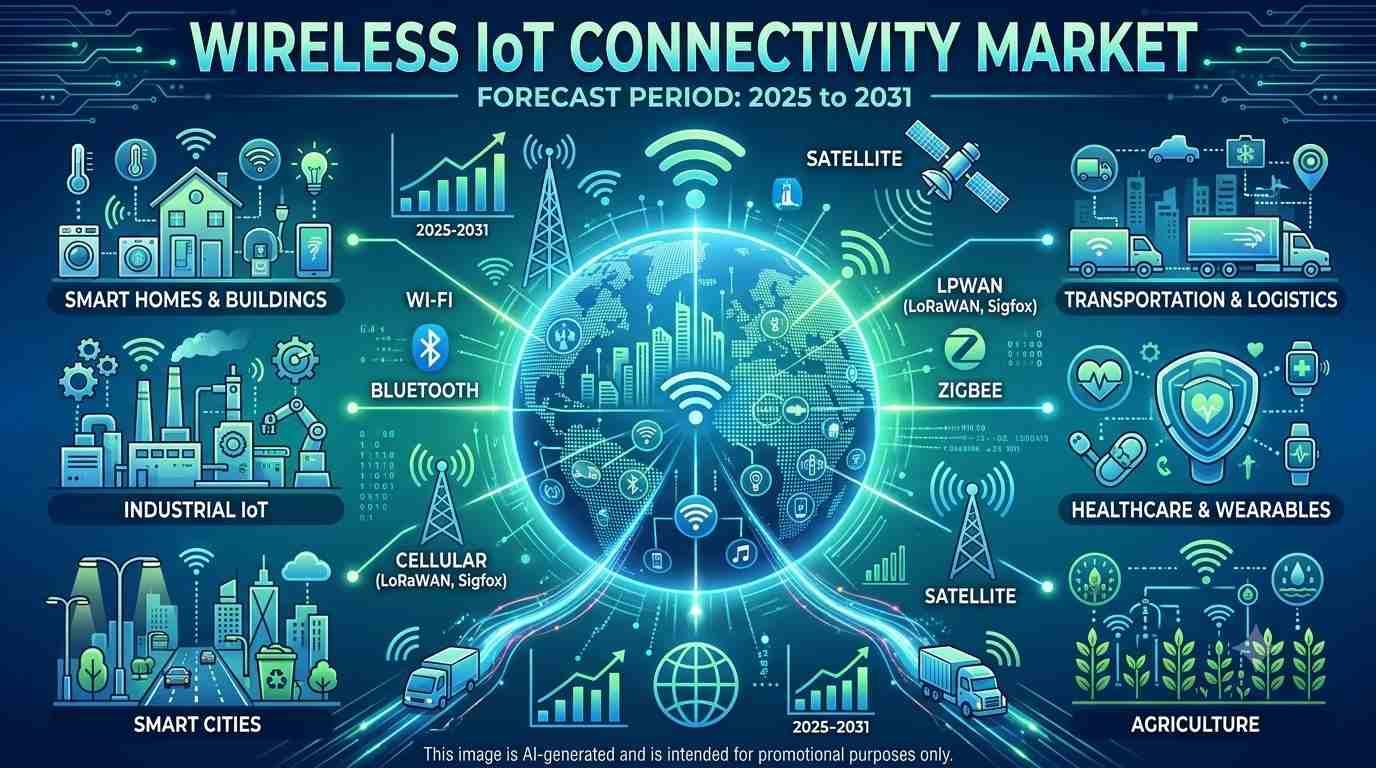
The Wireless IoT Connectivity Market in the United States is expanding as businesses across manufacturing, healthcare, transportation, retail, energy, and smart infrastructure increasingly adopt connected devices and wireless communication technologies. The growing deployment of IoT-enabled sensors, industrial automation systems, connected vehicles, smart buildings, and remote monitoring solutions is supporting demand for reliable and scalable wireless connectivity.
The Wireless IoT Connectivity Market size is expected to reach US$ 288.77 Billion by 2031. The market is anticipated to register a CAGR of 13.6% during 2025-2031.
What is driving the market?
Enterprise digital transformation, industrial automation, and expanding smart grid initiatives are the principal growth drivers. Device manufacturers and facility operators are increasingly required to ensure continuous uptime, support high device densities, and address zero-trust cybersecurity standards across connected endpoints. Automotive OEMs, healthcare providers, logistics operators, and smart city planners are seeking reliable, low-latency connectivity solutions that improve operational visibility without inflating power consumption or hardware overhead.
The transition is moving beyond basic device tethering toward intelligent, scalable connectivity ecosystems. Connectivity providers are investing in eSIM/iSIM technologies, multi-mode radio chipsets, low-power wide-area networks (LPWAN), and seamless hybrid satellite-terrestrial networks. Fragmented network protocols, legacy infrastructure interoperability, and spectrum congestion remain important constraints.
Which region leads?
Asia Pacific leads the market, accounting for an estimated 36%–40% share in 2025, and is also the fastest-growing region with a projected CAGR of 14.1%–15.2%. Growth is supported by rapid industrialization, massive smart city programs, high consumer electronics adoption, and aggressive 5G infrastructure rollout. China, Japan, South Korea, and India present significant opportunities as expanding IoT deployments coincide with government initiatives focused on digital infrastructure and intelligent manufacturing.
North America holds an estimated 27%–31% share, supported by early adoption of enterprise IoT platforms, robust healthcare technology integration, and private 5G deployments. Europe accounts for approximately 22%–26%, with demand driven by industrial automation (Industry 4.0), smart utility metering mandates, and connected automotive ecosystems.
Which segment leads?
Cellular (5G, LTE-M, NB-IoT) and Short-Range Wireless (Wi-Fi, Bluetooth) are the leading connectivity tech segments, representing an estimated 42%–46% of market revenue in 2025. Their dominant position is supported by widespread network coverage, mature ecosystem standardization, high bandwidth capabilities, and rapid integration into consumer and enterprise hardware. LPWAN technologies (LoRaWAN, Sigfox, NB-IoT) represent a high-growth category, forecast to grow at a CAGR of 15.8%–16.9% through 2033 due to expanding utility and agricultural monitoring applications.
By end-use industry, Industrial & Manufacturing leads with an estimated 32%–36% share in 2025, reflecting large-scale deployments of connected sensors, predictive maintenance systems, and automated machinery. Smart Utilities & Transportation is identified as a high-growth end-use segment, driven by smart grid modernizations, fleet management, and connected logistics solutions.
Which companies are prominent?
The report identifies Qualcomm Technologies, Inc., Nordic Semiconductor, Texas Instruments, Telit Cinterion, Sierra Wireless (Semtech), Quectel Wireless Solutions, AT&T Inc., Vodafone Group, Huawei Technologies, and NXP Semiconductors as prominent market participants.
These companies compete across wireless chipsets, connectivity modules, IoT gateways, managed connectivity services, and edge-to-cloud security platforms. Strategic differentiation increasingly depends on module power efficiency, multi-protocol flexibility, global roaming integration, embedded security features, and edge computing capabilities. The list reflects the report's competitive landscape rather than a revenue-ranked market-share table.
What is changing in 2026?
The market is shifting from basic device connection toward integrated, enterprise-grade, security-hardened connectivity frameworks. Technical specifications increasingly mandate built-in zero-trust authentication, remote eSIM provisioning, adaptive bandwidth management, and edge-AI processing compatibility. Regulatory frameworks surrounding data privacy and critical infrastructure protection—such as updated cyber resilience standards across major markets—are setting stricter compliance baselines for IoT network architecture.
Hardware vendors and network operators are accelerating low-power 5G RedCap (Reduced Capability) chipsets, satellite-direct-to-device connectivity standards, and energy-harvesting sensors. Procurement decisions are increasingly tied to end-to-end lifecycle security, total cost of connectivity, network reliability SLAs, and seamless platform interoperability.
What are the major investment opportunities?
The strongest opportunities lie in 5G RedCap technology, hybrid satellite-terrestrial IoT networks, edge-AI connectivity chipsets, and managed IoT security platforms. Investment in non-terrestrial networks (NTN), private cellular network deployment, and ultra-low-power radio architectures can capture growing demand across remote assets, maritime logistics, and precision agriculture.
Additional opportunities include high-density LPWAN infrastructure, automated eSIM/iSIM management platforms, and energy-harvesting wireless modules. As-a-service connectivity models and unified device-to-cloud software suites are expected to create recurring revenue streams as enterprises look to simplify multi-region IoT deployment, asset tracking, and data management at scale.
Asia Pacific offers attractive expansion potential through rapid enterprise adoption and massive infrastructure programs. Investors should prioritize providers offering modular hardware, robust cyber resilience, low power draw, and cross-standard interoperability tailored to diverse regional carrier networks.
The Insight Partners provides comprehensive syndicated and tailored market research services in the healthcare, technology, and industrial domains. Renowned for delivering strategic intelligence and practical insights, the firm empowers businesses to remain competitive in ever-evolving global markets.
• Email: sales@theinsightpartners.com
• Website: theinsightpartners.com
• Phone: +1-646-491-9876

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
