Global Non-Destructive Testing Market Forecast to Reach USD 17.16 Billion by 2036
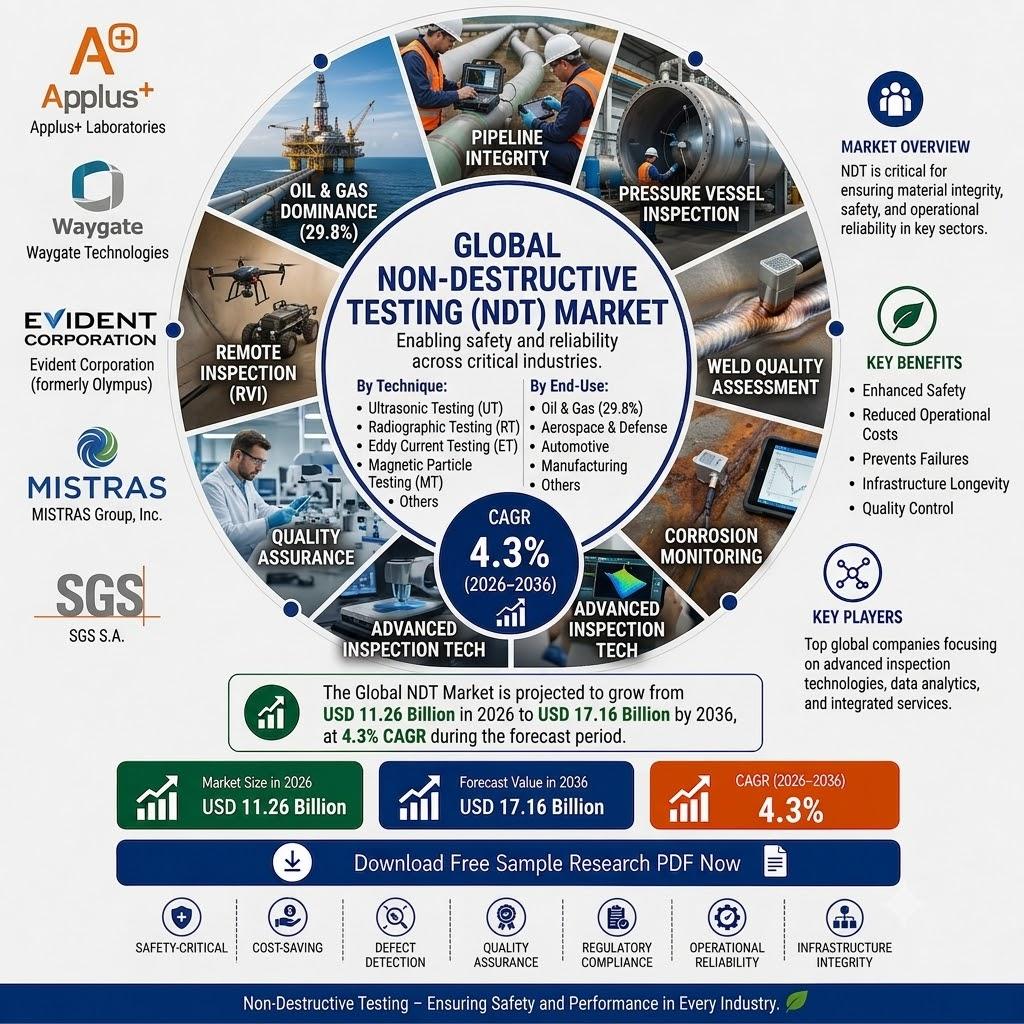
The global Non-Destructive Testing Market is estimated at USD 11.26 billion in 2026 and is forecast to reach USD 17.16 billion by 2036, expanding at a CAGR of 4.3%, according to Fact.MR analysis.
The market was valued at approximately USD 10.8 billion in 2025. Between 2026 and 2036, the market is expected to create an absolute dollar opportunity of USD 5.90 billion as industrial operators increase inspection requirements for safety-critical assets and production systems.
Oil and gas represents the largest end-use demand base, accounting for 29.8% of the market. Pipeline integrity, pressure vessel inspection, weld quality assessment, and corrosion monitoring are among the applications creating specification-intensive NDT requirements.
Fact.MR is a market research and consulting firm that provides industry intelligence, market forecasts, competitive analysis, and strategic insights across global markets.
Get detailed market forecasts, competitive benchmarking, and pricing trends: https://www.factmr.com/connectus/sample?flag=S&rep_id=4665
Oil and Gas Remains a Major NDT Demand Center
The oil and gas industry accounts for 29.8% of end-use demand in 2026. Inspection requirements are closely linked to pipeline integrity and the operating condition of pressure vessels, welds, and other critical infrastructure.
The economic case is direct. Inspection costs are measured against the potential cost of equipment failure, production disruption, or safety incidents. This keeps NDT relevant across both established industrial markets and regions adding new infrastructure.
Aerospace manufacturing is another specification-intensive application. Composite structures, turbine components, and safety-critical parts require NDT inspection at multiple production stages, with some applications requiring 100% inspection.
Advanced inspection technologies are also changing how defects are identified. Phased array ultrasonics, digital radiography, and eddy current array technologies are increasingly being applied across major end-use industries.
Ultrasonic Testing Equipment Holds 26.9% Product Share
Ultrasonic Testing Equipment accounts for 26.9% of the product segment in 2026, giving it the leading position by product value in the near term.
Established buyer preferences and compatibility with existing inspection infrastructure support continued demand for ultrasonic systems. The segment is also used across multiple industrial applications where reliability, specification compliance, and operating cost influence procurement decisions.
Inspection Services represents 41.2% of the service segment in 2026. Service providers compete through technician certification, geographic coverage, equipment capabilities, and their ability to support broader asset integrity programs.
Volumetric Testing Methods accounts for 38.5% of the technique segment in 2026, reflecting continued demand for methods capable of examining internal conditions within industrial components and structures.
AI-Assisted Inspection Creates a New Technology Focus
Artificial intelligence is becoming a notable area of development within NDT. AI algorithms can detect and classify defects using ultrasonic, radiographic, and visual inspection data.
For routine inspections, AI-assisted systems can reduce interpretation variability and support automated pass/fail decisions. Deep learning models trained on defect databases are also being developed to reach detection performance comparable to, or higher than, human inspectors for specific defect categories.
Waygate Technologies (Baker Hughes) introduced an AI-enabled phased array ultrasonic platform in 2025 with automated defect recognition and classification capabilities for pipeline and pressure vessel inspection.
Evident Corporation launched an enhanced portable phased array ultrasonic system in 2025, adding improved resolution, faster scanning, and cloud-connected data management for field inspection applications.
Eddyfi Technologies expanded its advanced eddy current array portfolio in 2026 for heat exchanger and tube inspection, targeting the inspection requirements of aging industrial infrastructure.
Mexico Leads Country Growth at 4.6% CAGR
Mexico is projected to record a 4.6% CAGR through 2036, making it the fastest-growing country market covered in the Fact.MR study. Oil and gas pipeline inspection, nearshoring-related manufacturing quality requirements, and infrastructure construction support demand.
Germany follows with a projected 4.2% CAGR through 2036. Aerospace and automotive quality systems, rail infrastructure inspection, and energy transition projects shape the country's NDT demand.
France is projected to expand at a 4.0% CAGR, supported by aerospace manufacturing, nuclear power inspection, and rail infrastructure. The country's nuclear fleet provides a concentrated source of recurring inspection requirements.
The United Kingdom is forecast to grow at 3.7% CAGR. North Sea oil and gas, aerospace, nuclear decommissioning, and offshore wind infrastructure contribute to demand.
South Korea is projected to expand at a 3.6% CAGR through 2036, with shipbuilding, nuclear power, and semiconductor manufacturing supporting precision inspection requirements.
Shambhu Nath Jha Highlights Shift Toward Data-Driven Inspection
Shambhu Nath Jha, Principal Consultant at Fact.MR, said, “The non-destructive testing market is fundamentally driven by the economic logic that the cost of inspection is a fraction of the cost of failure.”
He added that oil and gas, aerospace, nuclear, and infrastructure operators cannot afford to identify defects through operational failure. According to Jha, the industry is moving from manual, skill-dependent inspection toward technology-enabled, data-driven integrity management.
“Phased array ultrasonics, digital radiography, and AI-assisted defect recognition are changing the equation,” Jha said. “Vendors that bring advanced inspection technology together with data analytics and asset integrity management services will be better positioned for high-value contracts.”
Competitive Landscape
The competitive environment spans equipment manufacturers and inspection service providers. Applus+ Laboratories, Waygate Technologies (Baker Hughes), Evident Corporation (formerly Olympus), and MISTRAS Group, Inc. hold established positions through inspection equipment, service capabilities, certified workforces, and relationships across major end-use industries.
SGS S.A., Bureau Veritas S.A., Intertek Group plc, Sonatest Ltd., Eddyfi Technologies, and Zetec Inc. also participate across equipment and service categories.
Competition increasingly includes technology capability. PAUT, digital radiography, AI-enabled defect recognition, certification scope, and geographic coverage are among the factors shaping competitive positioning.
To View Top reports
https://net-pals.com/blogs/33448/Global-Quantum-Computing-Advanced-Packaging-Market-Set-to-Reach-USD
About Fact.MR
Fact.MR is a market research and consulting firm providing independent market intelligence, forecasts, competitive benchmarking, and strategic analysis. Its research combines secondary research, primary interviews, and quantitative forecasting models to assess market size and future demand.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Romaian
 Portuguese (Brazil)
 Greek